
 By admin
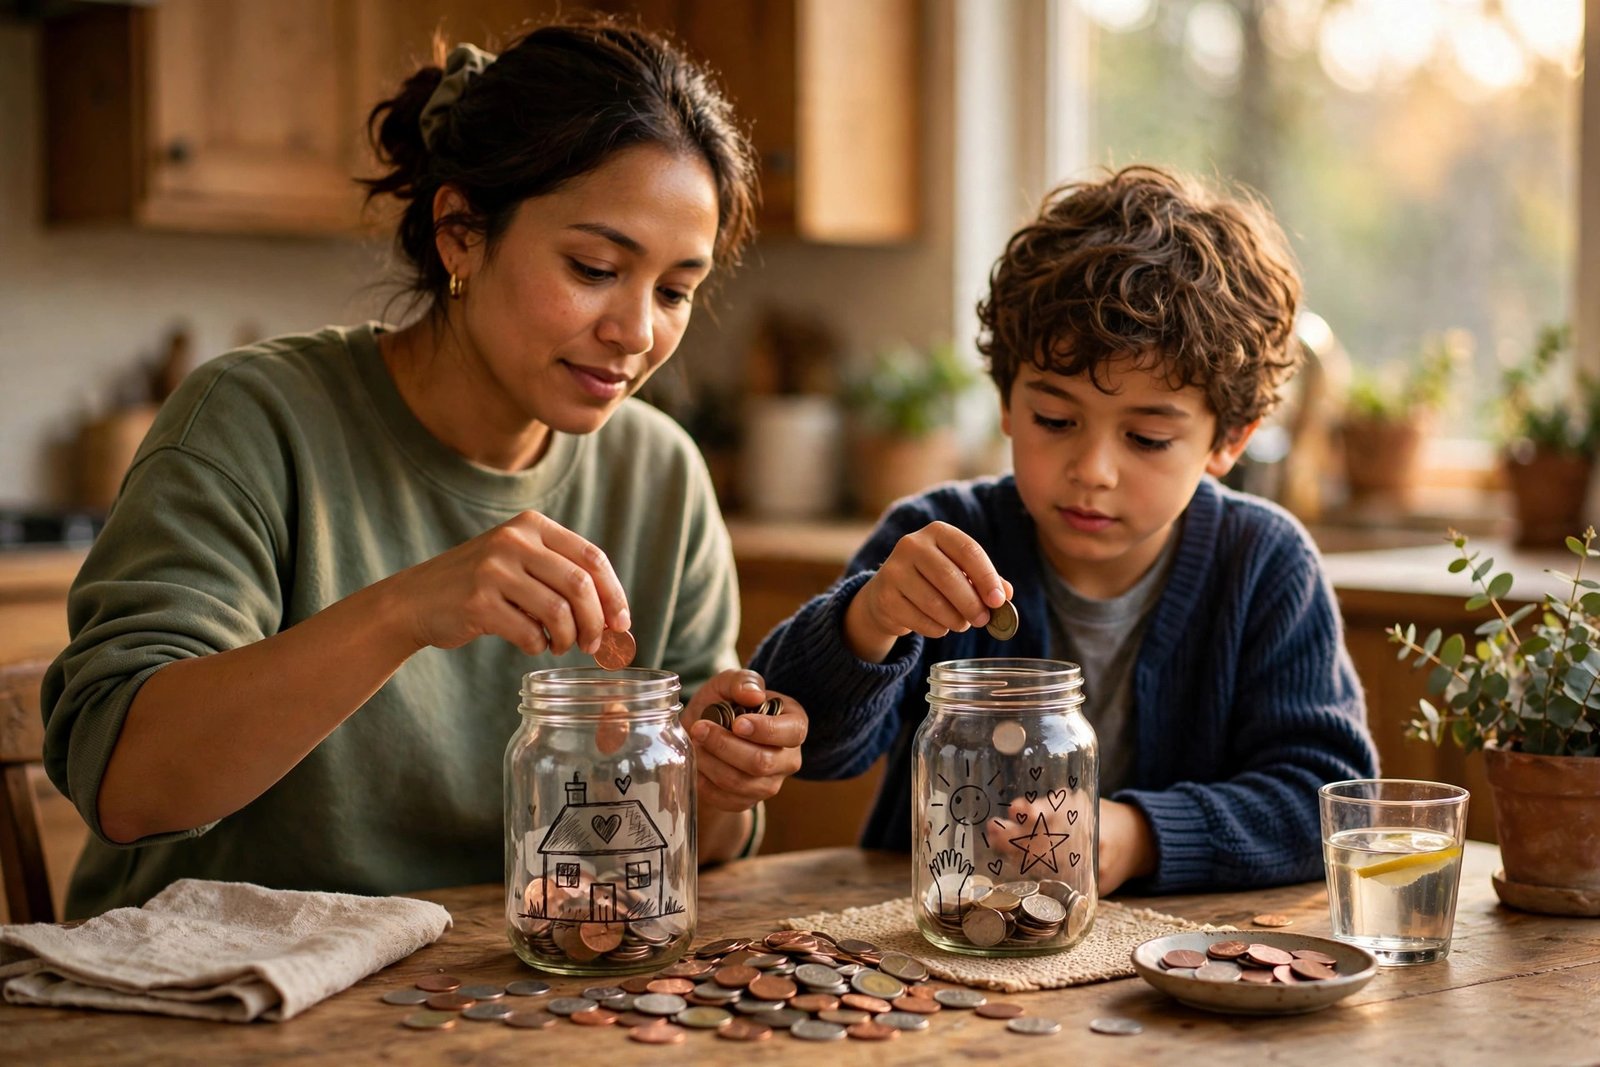
Every parent knows the scene: you start explaining compound interest, your kid’s eyes glaze over by sentence two, and you’ve somehow made money boring and stressful in under a minute. Lecturing about money doesn’t work on kids for the same reason it doesn’t work on adults — nobody learns financial wisdom from being talked at. Kids learn money the way they learn everything: by doing, watching, and making small mistakes while the stakes are low.
This guide shows how to teach your kids about money without lecturing — through systems, games, and everyday moments that build genuine financial intuition before they ever need it.
Why Lecturing Fails (and What Works Instead)
Children (like adults) tune out abstract advice but absorb lived experience. Telling a seven-year-old to “save 20 percent” is noise; giving them a clear jar where they watch coins accumulate toward a toy they want is education. The research on financial socialization is consistent: kids’ money habits are shaped far more by what they observe and practice than by what they’re told. Your behavior is the curriculum — the conversations just annotate it.
The goal isn’t raising miniature accountants. It’s building three intuitions before adulthood: money is finite (opportunity cost), waiting is powerful (delayed gratification), and earning precedes spending (no magic money). Everything else is details.
The Systems: Make Money Visible and Hands-On
The three-jar method (ages 4–10)
Give allowance or earnings three destinations: Spend, Save, Share. Clear jars beat piggy banks because kids see accumulation. Let them make real decisions — including bad ones. The $5 toy that breaks in a day teaches more about value than any lecture on frugality. Resist the urge to veto; small mistakes now prevent large ones later.
The parent-bank (ages 8–14)
Offer interest on savings — 5–10 percent monthly, paid by you. A kid who watches $50 become $55 in a month feels compounding in a way no explanation delivers. It’s the most powerful financial lesson you can buy, and it costs you a few dollars.
Real accounts (teens)
A teen checking account with a debit card, then a Roth IRA once they have earned income — there’s no minimum age for a custodial Roth, and decades of tax-free compounding on teen earnings is an extraordinary gift. Walk them through statements together monthly; financial literacy is a practice, not a lesson.
Everyday Moments That Teach (No Lecture Required)
Grocery shopping: Give older kids the list and a budget for one category — comparing unit prices and making tradeoffs is applied mathematics with real stakes. (You’ll also find grocery savings strategies useful for the family budget overall.)
Waiting for wants: Institute a 30-day list for non-essential wants. Most items lose their urgency within weeks — kids discover this themselves, which is infinitely more persuasive than being told. What survives the month is genuinely wanted; buy it guilt-free.
Earning, not just receiving: Tie some money to effort — extra chores, neighborhood jobs, selling outgrown items. The connection between work and money is the foundation everything else builds on. An allowance with no effort attached teaches that money appears; earned money teaches that it doesn’t.
Talk about your decisions out loud: “We’re choosing the used car so we can afford the vacation” — narrating tradeoffs normalizes the idea that money involves choices, not just amounts. Kids who hear parents discuss money calmly grow into adults who handle it calmly. The CFPB’s Money as You Grow offers excellent age-by-age conversation guides.
What to Teach at Each Age
Ages 4–7: Money is exchanged for things; some things cost more; waiting gets you more. Keep it concrete and physical — coins and jars, not concepts.
Ages 8–12: Budgeting basics (the jars evolve into categories), the difference between needs and wants, introduction to earning. This is the golden window — old enough to understand, young enough to listen.
Ages 13–17: Real accounts, part-time work economics (that $200 sneaker costs 25 hours of work — the labor-price conversion is sobering and effective), introduction to investing and compound growth, and the credit card conversation before they turn 18. Jump$tart Coalition’s resources offer frameworks for teen financial education.
Mistakes Parents Make (Gentle Corrections)
Rescuing every bad purchase. The broken toy bought against your advice is tuition, not tragedy. Bailouts teach that consequences are optional.
Fighting about money in front of kids. Disagreements are normal; visible anxiety and conflict teach kids that money is scary. Discuss calmly, or privately.
Waiting until they’re “old enough.” By the teen years, habits are largely set. Start at four with jars; the concepts scale with the child.
Making it all about restriction. Kids who only hear “we can’t afford it” learn scarcity. Balance with “we’re choosing this instead” — agency, not deprivation. For the broader family money picture, building kids’ money habits complements these strategies.
Money Mistakes to Let Them Make
The hardest part of teaching kids about money is also the most important: letting them fail small. The overpriced toy that breaks, the savings blown on something forgotten in a week, the “investment” in a friend’s dubious scheme — each is a lesson that lands precisely because it stings a little. Parents who prevent every mistake raise kids who make their first financial error at 22 with a credit card instead of at 9 with allowance.
Set the guardrails, then step back. Guardrails: the amounts are small enough to absorb, the mistakes are reversible, and you’ll discuss afterward without shaming. Then let the consequences teach. The post-mistake conversation is where the learning crystallizes — not “I told you so,” but “what would you do differently?” Kids who’ve felt the disappointment of a wasted $20 develop an intuitive frugality no lecture can install. Your job isn’t to raise a child who never errs with money; it’s to raise one who’s made all the cheap mistakes before the expensive ones arrive.
Conclusion
Teaching kids about money without lecturing means building systems (jars, parent-bank interest, real accounts), seizing everyday moments (shopping, waiting lists, narrated tradeoffs), and letting small mistakes teach what words can’t. You don’t need a curriculum — you need consistency, visible behavior, and the patience to let a $5 mistake do the teaching. Start this week with one jar and one conversation. The compound interest on that investment runs for a lifetime.
Frequently Asked Questions
How much allowance should I give?
There’s no magic number — many families use $1 per week per year of age as a starting point. What matters more than the amount is the system around it: the jars, the decisions, the consequences. Adjust for your budget without guilt.
Should kids have to earn their allowance?
A hybrid works best: a base allowance (teaches budgeting with predictable income) plus opportunities to earn extra (teaches the work-money connection). Tying all money to chores can backfire — kids may refuse necessary family contributions without pay.
At what age should I open a bank account for my child?
Savings accounts work from any age (custodial); checking with a debit card makes sense around 13–15. A custodial Roth IRA can be opened as soon as they have earned income — even a 14-year-old’s summer job qualifies.
How do I teach teens about credit cards?
Before 18: explain how they work using your own statements (redacted), emphasizing that the minimum payment trap turns a $1,000 purchase into a $1,300 one. At 18: consider a secured card or authorized-user status with a strict pay-in-full rule. The lesson is “credit is a tool, not money.”